Western Mountains & Flathead
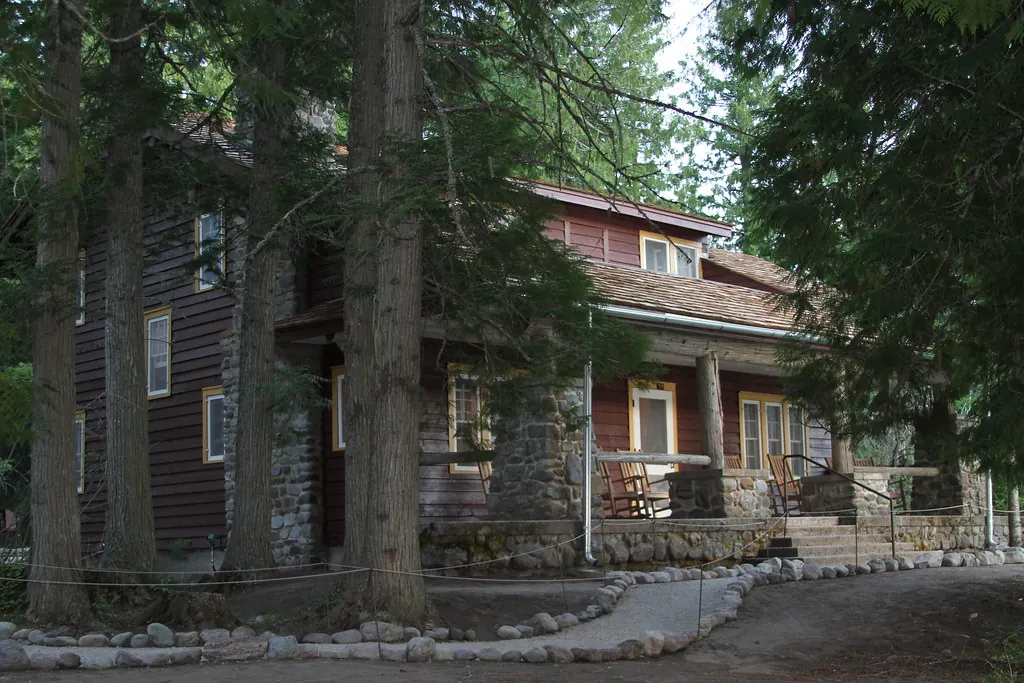
Missoula · Kalispell · Whitefish · PolsonWildfire and smoke, heavy mountain snow, falling timber and lake cabins with seasonal occupancy.
Independent property claim appraisal · all 56 counties
For hail, wind, wildfire and winter claims that came back short.
When your insurer accepts the claim but the payment won’t put the roof, the walls or the barn back, Montana Insurance Appraiser builds an independent, line-by-line valuation and takes it through the appraisal clause in your policy.
Why people call us
Most underpaid Montana claims aren’t denied. They’re short: a roof slope missing from the estimate, steel siding priced as a patch, a pole barn left off, ice-and-water membrane nobody counted.
Montana Insurance Appraiser works in the space between “covered” and “paid in full.” When either side invokes the appraisal clause, each names an appraiser, and the two of them, with an umpire if needed, set the amount of loss. As your Montana Insurance Appraiser, we build the number you take to that table and defend it item by item.
How our firm works
We’re appointed by you and owe the carrier nothing but a fair, supportable number.
Every valuation starts with our own inspection, photos and measurements.
A full estimate priced for your part of Montana, not a percentage guess.
Claim services
From a quick estimate review to full appraisal clause representation and neutral umpire work, built around the losses Montana actually gets.
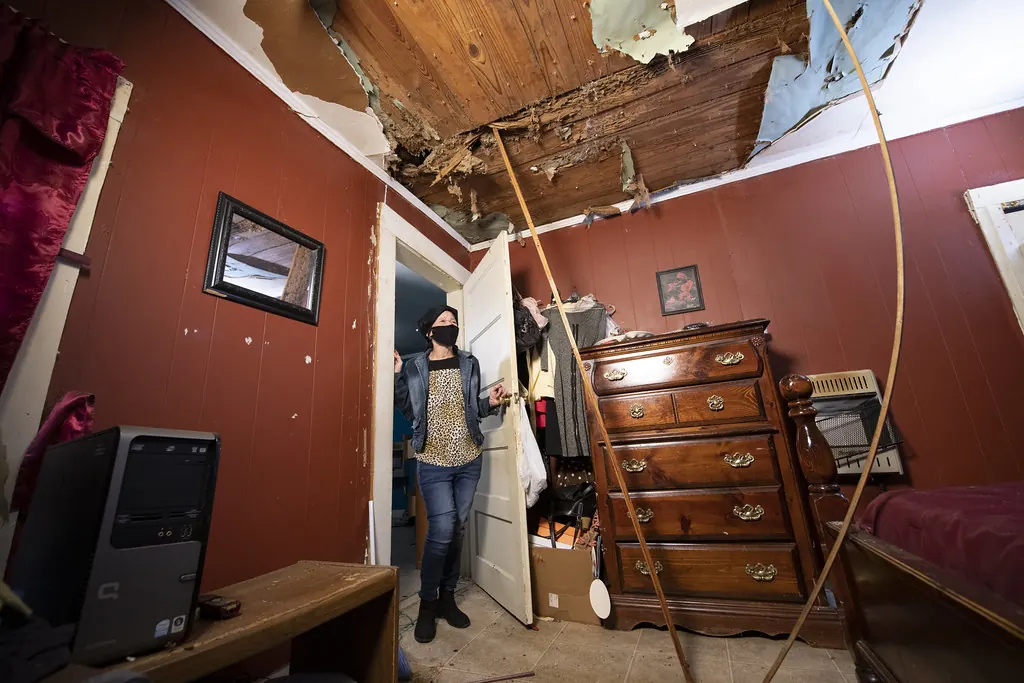
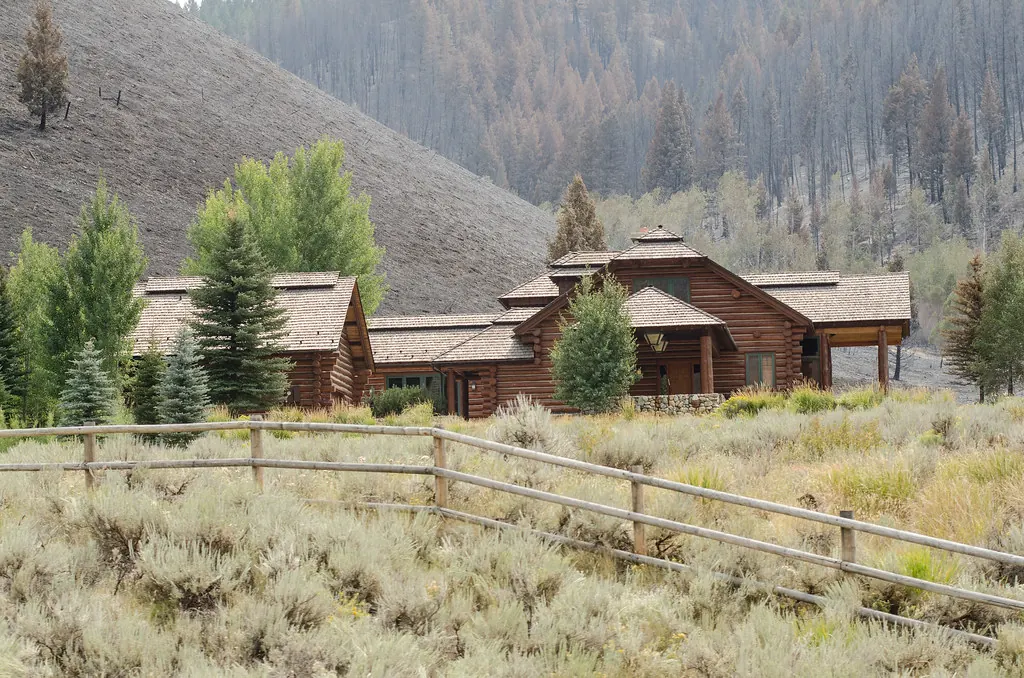
Claim seasons
A Montana Insurance Appraiser has to know what each season does to a building. Here’s when the calls come in.
Four Montanas
Montana is the fourth-largest state, with 56 counties and terrain from glaciated peaks to badlands. A Montana Insurance Appraiser working in Whitefish faces different losses than one working in Miles City, and the estimate has to show it.
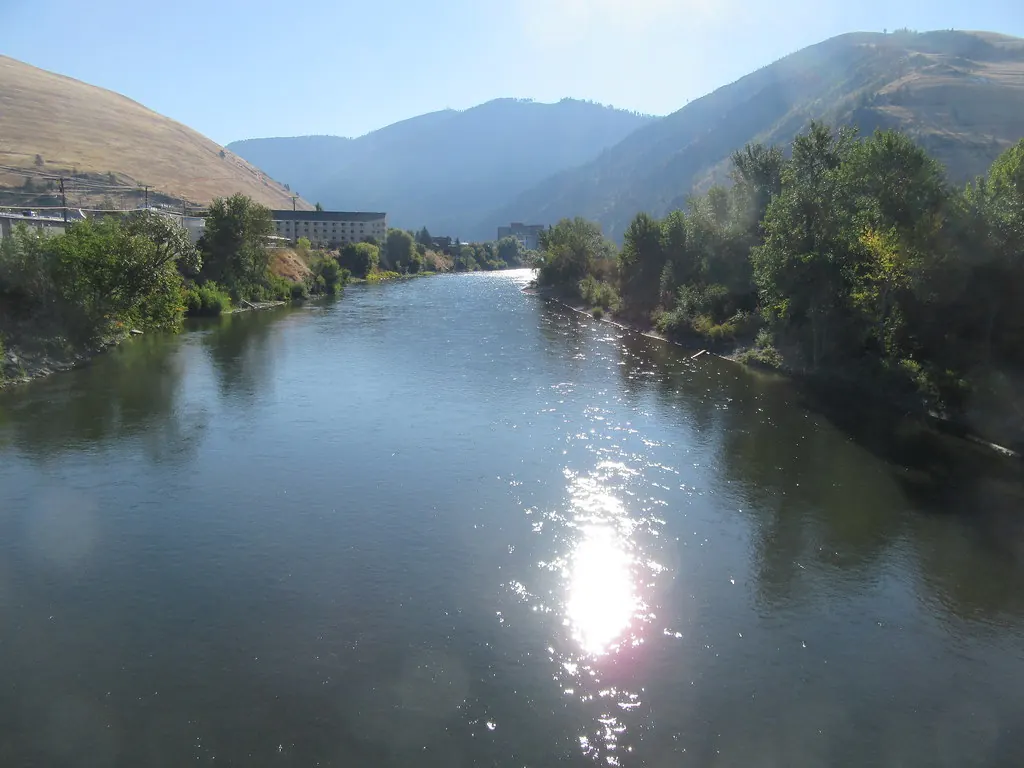
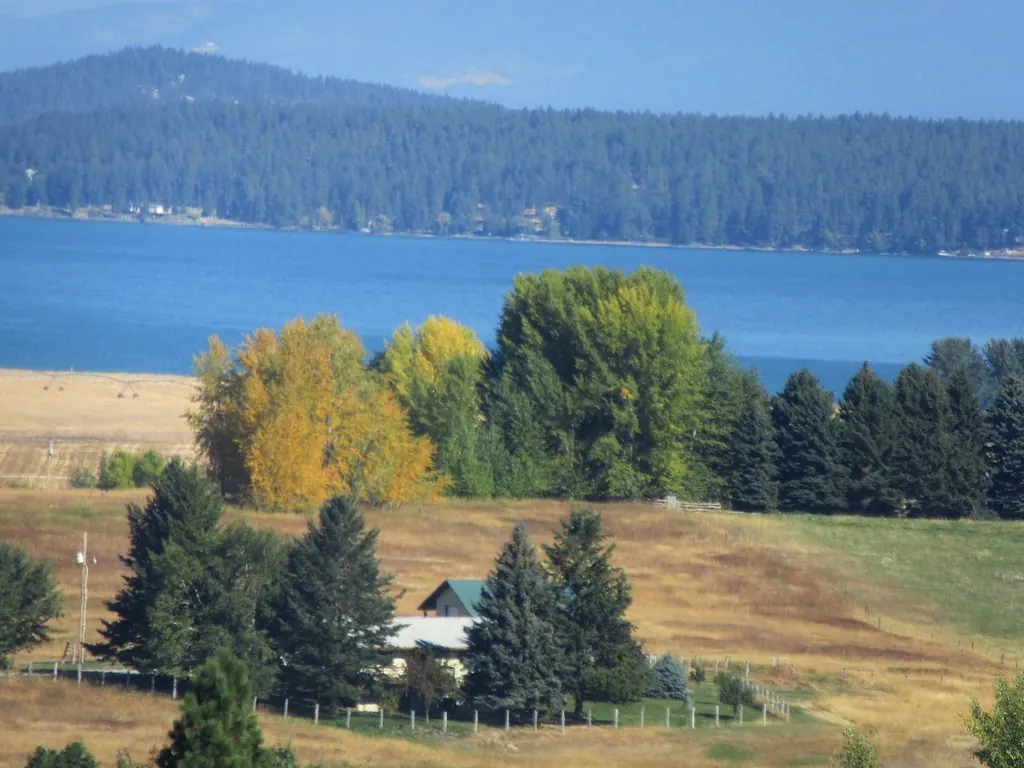
Wildfire and smoke, heavy mountain snow, falling timber and lake cabins with seasonal occupancy.
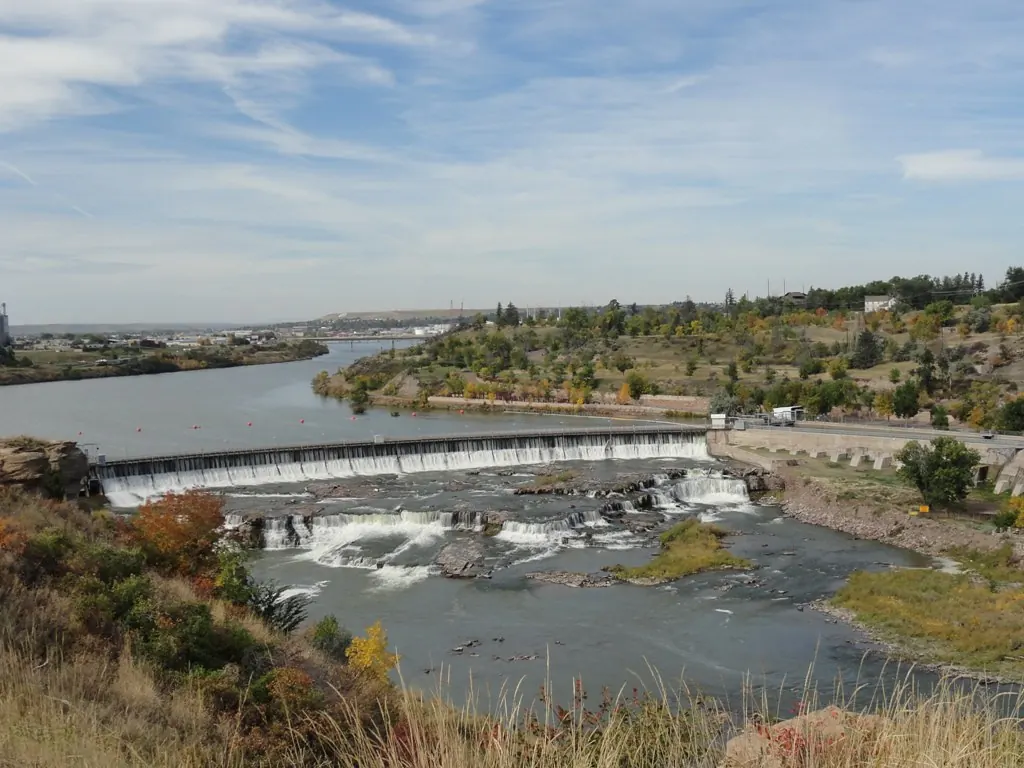
High building costs, snow load, fierce valley winds and older brick and frame homes.
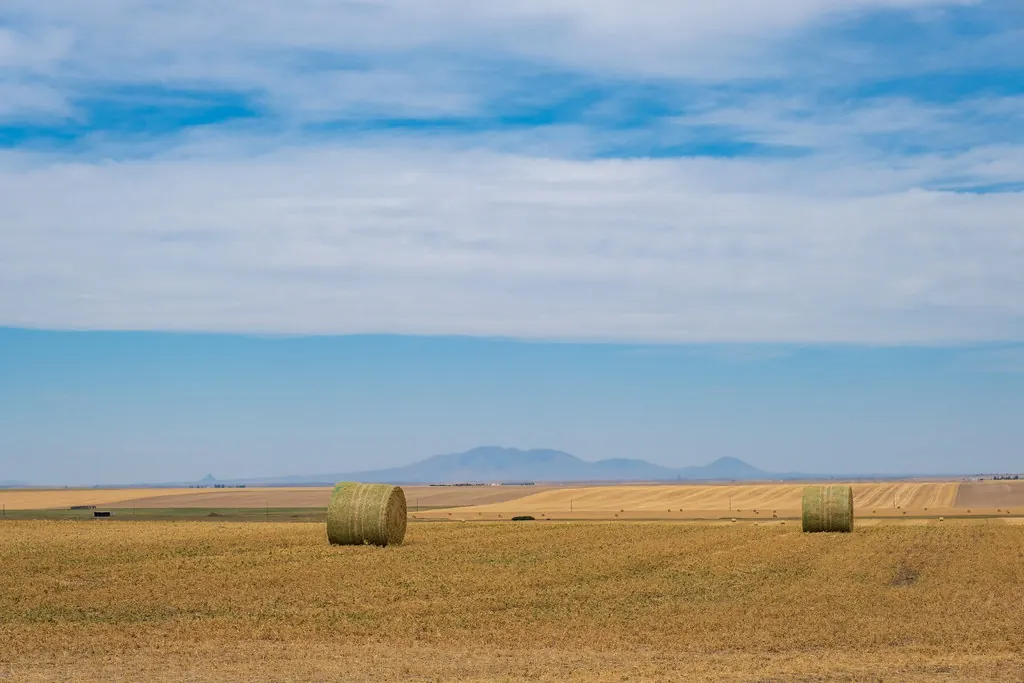
Chinook winds, hard hail, sudden temperature swings and long distances for contractors.
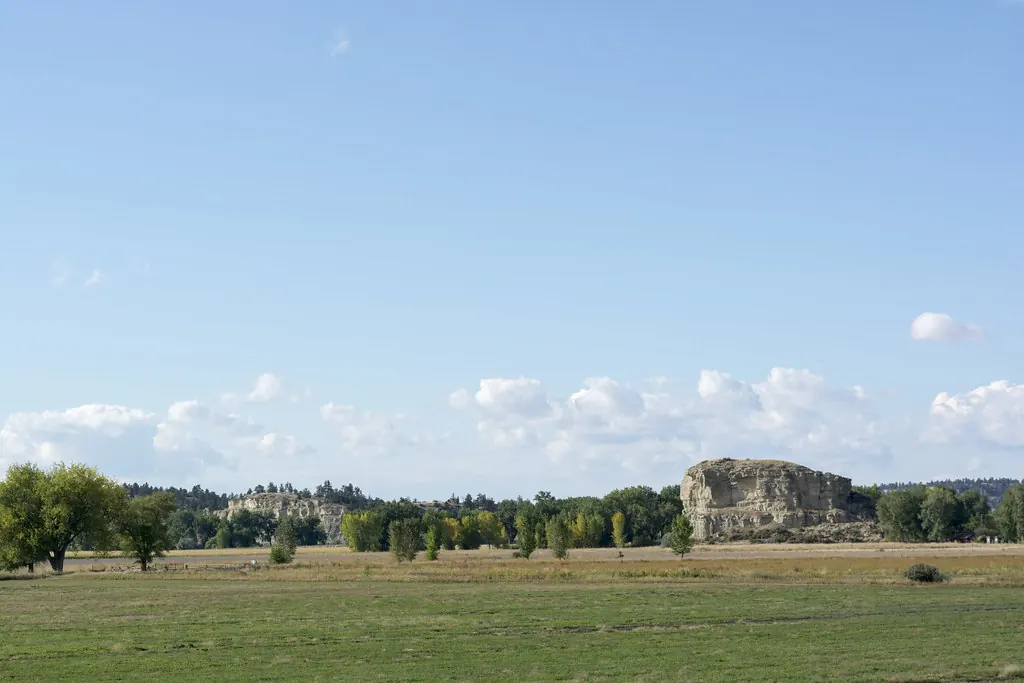
Montana’s busiest hail corridor, thunderstorm winds, river flooding and grass fires.
The process
The appraisal clause turns an open-ended argument into a defined process with a binding answer on the amount of loss.
Read the full appraisal roadmapSend the policy, the carrier’s estimate and your photos. A Montana Insurance Appraiser reads them and tells you plainly whether appraisal fits.
We inspect, measure and photograph, then build a line-item estimate priced for your area and season.
Appraisal is demanded in writing and we’re named as your appraiser within the policy’s timeline.
We go line by line with the carrier’s appraiser. Most differences narrow sharply here.
Anything still open goes to a neutral umpire. Two signatures set the amount of loss, and payment follows.
Try it now
Depth alone doesn’t tell you much. Twenty inches of wind-packed snow weighs far more than twenty inches of fresh powder. Enter what’s up there for a quick, illustrative estimate.
The full roof snow load estimator handles multiple layers, roof area and total weight. It’s one of seven free tools from Montana Insurance Appraiser.
Free claim toolkit
Check the carrier’s math before you pick up the phone. Everything runs in your browser; nothing is stored or sent.
 CalculatorCalculatorCalculator
 Calculator
 PlannerChecklist
 Estimator
Montana cities
We take claims statewide. These twelve local pages cover the communities we hear from most.
Straight talk
A good Montana Insurance Appraiser will tell you when to look elsewhere. Here’s the short version.
Questions
Plain answers on how appraisal works, what it costs and when it’s the wrong move.
We value property damage when you and your insurer agree the loss is covered but disagree on what it costs. As your appointed appraiser we inspect, write an independent line-item estimate, work with the carrier’s appraiser and, if needed, present open items to a neutral umpire.
No. A public adjuster manages and negotiates a whole claim. An appraiser works inside the policy’s appraisal clause on one question: the amount of loss. We don’t negotiate outside appraisal and we don’t give legal advice.
Usually when coverage has been accepted, you have the carrier’s full estimate, and the gap between it and a qualified contractor’s estimate is meaningful, often more than about 10% or several thousand dollars. Our claim gap calculator helps you test that.
On the amount of loss, generally yes, once two of the three panel members sign. The award doesn’t decide coverage questions, and your policy wording controls.
Each side pays its own appraiser and usually half of any umpire. We put fee terms in writing before work begins, and the first conversation costs nothing.
Yes. We take claims in all 56 Montana counties, from mountain towns and lake cabins to ranches on the eastern plains.
Field notes
Practical, Montana-specific guides on policy language, documentation and timing.
A plain-language walk through the appraisal clause in Montana property policies, phrase by phrase. Learn what it can decide, what it can’t and when it’s the wrong tool.
Why hail roof disputes are so common in Montana and what decides them. Covers test squares, matching, metal roofs, deductibles, payment schedules and missed items.
Wildfire claims in Montana range from total losses to smoke damage in homes the fire never touched. Here’s what drives disputes and how to document them.
Start here
Tell us what happened and what the carrier offered. You’ll get a straight answer on whether appraisal is worth pursuing, with no pressure.

